About
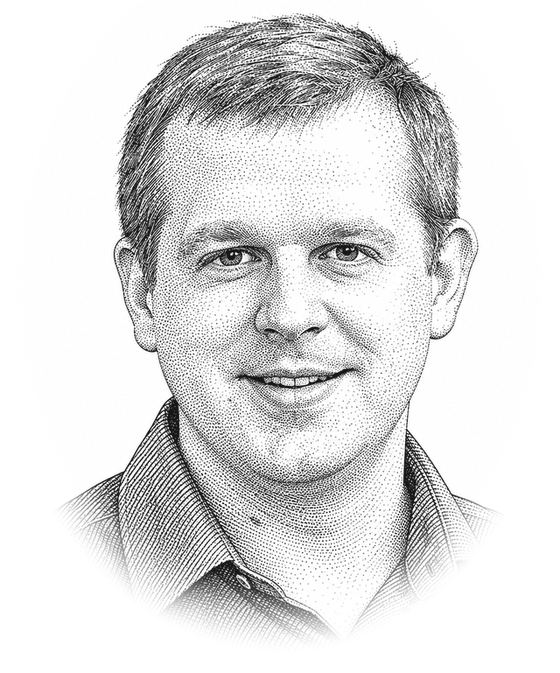
I studied Economics and Political Science at Gonzaga University, followed by M.A. and Ph.D. degrees in Economics from George Mason University. My doctoral dissertation examined corporate strategies for managing regulatory risk, and the underlying question, how a business copes with risks outside its control, still shapes how I evaluate companies today.
I’m a published textbook author and I’ve been quoted in financial publications including Business Insider, Bankrate, Consumer Reports, MSN Money, and others.
Before opening my independent practice, I worked in the Greater Los Angeles area providing advice on public pension and retirement plans for teachers. My wife, Melanie, is an Assistant Professor of Economic History at the London School of Economics.
Now with over 10 years of experience in the wealth management industry, I have no interest in building an empire, supervising teams of advisors, or running a national marketing effort. These days my time is mostly dedicated to research. I want to lead a decent lifestyle with my family, focus on the work that I love, and help my clients do the exact same.
Will I be able to help with your goals?
We Might Be a Good Fit If…
Your finances are mostly in order, but you’d rather not spend your time managing investments. Maybe you used to run your own portfolio and no longer want to, or you’re simply busy. You’d like someone else to handle it, while still being able to talk directly with the person making the decisions.
You’ve had a bad experience with another advisory firm. Perhaps you were burned by high-pressure sales tactics, or by high-fee products that were never clearly explained. I can help untangle that and get your plan back on track.
You’d rather work with an individual than a team. I don’t delegate. If you email a question, I’m the one who answers it, and if an investment decision is made in your account, the buck stops with me.
Probably Not a Good Fit If…
You want the prestige of a national brand. I certainly appreciate my clients, but I don’t hold client appreciation events.
You want detailed cash-flow projections. Planning software tries to estimate a lifetime of income and expenses, years into the future. My approach is to get directionally correct, then meet as often as needed to stay on track as things change.
Lowest cost is your main concern. A robo-advisor is the cheaper choice, and I generally don’t negotiate on fees.
You’d rather not work remotely. Meetings are by video call and most communication is by email, so I need to be able to reach you and stay in touch.
CERTIFIED FINANCIAL PLANNER® Certificant
 Nick Forbes Bormann is a CFP® professional. To earn CFP® certification, a candidate must meet CFP Board’s education requirements, pass the CFP® exam, complete a work experience requirement, and agree to follow CFP Board’s ethical standards, including a fiduciary duty when providing financial advice. Continuing education is required to maintain the certification.
Certified Financial Planner Board of Standards Center for Financial Planning, Inc. owns and licenses the certification marks CFP®, CERTIFIED FINANCIAL PLANNER®, and CFP® (with plaque design) in the United States to Certified Financial Planner Board of Standards, Inc., which authorizes individuals who successfully complete the organization’s initial and ongoing certification requirements to use the certification marks.